









NHIA (formerly NHIS) vs Private HMO Plans in Nigeria
Author Noella Lepdung
Introduction
Most people still say “NHIS”, but the scheme they mean is now run by the National Health Insurance Authority (NHIA). The NHIA Act 2022 replaced the old National Health Insurance Scheme (NHIS) with a broader regulator, and every Health Maintenance Organisation (HMO) — public-scheme HMO or private-plan HMO — is accredited by NHIA. So the question is not really “NHIS or HMO?” The two things are not opposites. The question is whether you should sit inside a public NHIA-run scheme (Formal Sector Scheme, state scheme, informal-sector scheme, vulnerable-group scheme) or buy a private retail health plan from an NHIA-accredited HMO — or use both.
This guide compares the two on the things that decide the answer for most Nigerian households: what you actually pay, what is covered, which hospitals you can use, how long you wait to be covered, how family members are treated, and what happens when you change jobs or move city. At the end, there is a short decision framework by household type, and a link to compare live private plans on nairaCompare.
What “NHIS” now means: NHIA and its public schemes
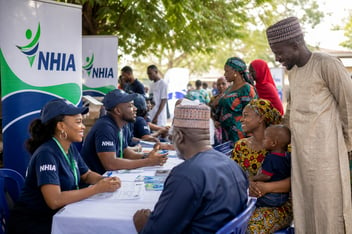
The NHIA Act 2022 makes health insurance mandatory in principle for every Nigerian and legal resident, and gives NHIA the mandate to regulate every HMO and to run several public schemes. The scheme most people call “NHIS” is really the Formal Sector Social Health Insurance Programme (FSSHIP) for federal public-sector employees, plus a group of related schemes for other groups. The old NHIS name still appears on payslips, ID cards and hospital forms, but the regulator, the rulebook and the branding are now NHIA. For a step-by-step walkthrough of how to enrol, when to expect a card and what to do if you cannot find your record, see the NHIA 2026 enrolment guide.
Public NHIA-run cover in Nigeria today falls into a few tracks:
- Federal Formal Sector Scheme (FSSHIP) — federal government workers and their registered dependants, funded by employer contributions.
- State Social Health Insurance Schemes — every state now has one (Lagos LASHMA, Oyo OYSHIA, Anambra ASHIA, FCT, and so on), with income-graded contributions and subsidised cover for the poorest. Our dedicated guide to state health insurance schemes in Nigeria walks through LASHMA, OYSHIA, ASHIA, FHIS and how to enrol in each.
- Vulnerable Group Fund (VGF) — created by the NHIA Act 2022 to subsidise cover for people who cannot pay, including indigent Nigerians, pregnant women and children under five.
- Tertiary Institutions Social Health Insurance Programme (TISHIP) — for students in participating universities and polytechnics.
- Informal Sector schemes — pooled arrangements for market groups, cooperatives and self-employed workers, run by NHIA-accredited HMOs.
Under all of these, the reader is enrolled with an HMO (the same kinds of HMO that also sell private plans) and uses a defined benefit package at accredited hospitals. That’s the point that trips people up: the HMO is the same type of company; what differs is the scheme it is delivering and the rules that go with it. For the full picture of what the law requires, see our pillar on the NHIA Act 2022 and what mandatory health insurance means for you.
What “private HMO plans” means
A private HMO plan is a retail health-insurance product you or your employer buys from an NHIA-accredited HMO on top of, or instead of, a public scheme. Providers such as Hygeia HMO, Bastion Health, AXA Mansard Health, AIICO Multishield, Sunu Health, NEM Health, HCI Healthcare, Leadway Health and Emple X Bastion sell tiered plans (typically named after gems, metals or fruit — Titanium, Sapphire, Ruby, Pearl, Strawberry, Blueberry, and so on) priced by benefit ceiling, hospital network and add-on cover. Retail plans on the nairaCompare marketplace are mostly individual and family plans, with senior-citizen tiers from selected HMOs.
Private plans are not a separate regulatory world. The HMO is accredited by NHIA, the plan sits inside NHIA’s operational rules, and NHIA can act on complaints. What you are paying for is a richer benefit package, a bigger hospital network, faster service and freedom to choose the plan — not a different regulator.
Public vs private: side-by-side
The two routes compare across ten decision factors most Nigerian households actually weigh. Entries below reflect how each route works in principle under the NHIA Act 2022; confirm specific premiums, benefit ceilings and hospital lists with the HMO or state agency before enrolling.
| Factor | Public NHIA scheme | Private HMO plan |
|---|---|---|
| Regulator | NHIA | NHIA (accredits every HMO) |
| Who pays | Employer, state scheme or Vulnerable Group Fund (subsidised) | You or your employer at full market premium |
| Entry cost | Low: contribution tied to income or scheme category | Higher: annual premium per person or per family |
| Benefit package | Defined by regulation; essentials-first | Tiered; broader on higher tiers |
| Hospital network | Scheme-specific NHIA list, often local | Wider private and tertiary hospitals (tier-dependent) |
| Pre-existing conditions | Covered subject to waiting periods and formulary | Frequently excluded on lower tiers; confirm per plan |
| Dependants | Defined number included; extras available for a contribution | Per-person premiums or family bundle at a headline price |
| Portability | Tied to employer or state; may need to re-enrol if you move | Travels with you if the HMO network covers where you are going |
| Service speed | Varies by HMO and state | Typically faster call handling and authorisation |
| Compliance with NHIA Act 2022 | Satisfies the mandate directly | Satisfies the mandate when the HMO is NHIA-accredited |
Each row is expanded in the sections that follow.
Cost: what you actually pay
Public NHIA schemes are funded by contributions tied to income or membership, not by a market-set premium. In the federal Formal Sector Scheme, the employer pays a percentage of the employee’s basic salary and the employee makes a smaller contribution; the household then uses the benefit package at zero point-of-service cost for most listed items. State schemes charge a flat annual contribution per adult in the informal tier (commonly a few thousand naira up to low tens of thousands, varying by state), with lower rates for children and full subsidies for the poorest under the Vulnerable Group Fund.
Private retail plans are priced as annual premiums per person or per family, and premiums rise with the size of the benefit ceiling, the hospital list and the number of dependants. Because premium tables change and each HMO structures its tiers differently, the honest way to plan a budget is to run the current numbers on the private-plan listing rather than trust a figure you saw last year. Bear in mind that the cheapest private plan is usually more expensive than an informal-sector NHIA contribution, and the most comprehensive private plans can cost several multiples of an entry-level tier.
Two consequences follow from this:
Especially where an employer already contributes on your behalf or the state subsidises your tier.
Not on being cheap in absolute terms.
Coverage: what each route pays for
NHIA benefit packages are defined by regulation. The public schemes cover primary care, common secondary care, routine antenatal and delivery, immunisations, defined chronic-disease drugs and hospital admissions within the agreed package. Some higher-cost services — advanced imaging, certain specialist procedures, non-formulary drugs and some cancer treatments — are excluded or capped, and readers are expected to use listed hospitals for the package to apply. The exact list and any recent updates should be confirmed with your HMO or on the NHIA website before you enrol.
Private retail plans compete on breadth of benefits within a tier: higher annual limits, wider drug formularies, more inpatient days, broader dental and optical cover, evacuation, wellness and second-opinion services. Higher tiers of Titanium, Sapphire, Ruby, Diamond, Platinum and equivalent plans typically add specialist imaging, more admissions, more hospitals and, on some plans, limited overseas referral. As a rule of thumb, a mid-tier private plan expands the same core services an NHIA scheme covers; a top-tier private plan adds services an NHIA package does not usually include.
Items to check line by line
Pre-existing conditions, maternity, mental-health cover and cover for dependants are handled differently by every plan. Treat them as items to check line-by-line in the benefit schedule rather than assume.
Provider network and access
Under NHIA schemes, you are usually assigned a primary care provider and must start there for non-emergencies, then get a referral if you need secondary care. The hospital list is set by the HMO’s NHIA network for that scheme and tends to lean towards public and mid-sized private hospitals in your enrolment location. Access is workable, but the network is not the whole country and it is not endlessly changeable.
Private plans typically give you a wider provider list and, on higher tiers, direct access to specialists and larger private hospitals without a mandatory GP referral. Emergency access at listed hospitals is straightforward on both routes; access outside your listed network is where the difference bites, especially when you travel between states.
Waiting periods and pre-authorisation
Public NHIA schemes generally have a short activation window — often a matter of weeks after your first contribution or employer enrolment — followed by immediate access to the core package, with maternity and a few high-cost services subject to defined waiting periods.
Private plans have their own waiting periods, especially for maternity (frequently around 10–12 months, plan-dependent), pre-existing conditions (often excluded outright on lower tiers) and elective procedures. Pre-authorisation for planned admissions, imaging and specialist reviews is standard on both routes, and delays there are a common complaint the reader should factor in. Confirm current plan waiting periods with the HMO before you pay.
Dependants and family cover
NHIA schemes let a principal enrol a defined number of dependants (commonly the spouse and up to four biological children under 18, with variations by scheme), and additional dependants can usually be added for an extra contribution. Vulnerable dependants may qualify for subsidised cover through the Vulnerable Group Fund.
Private plans handle families in two ways: per-person premiums added together, or family bundles at a headline price. Family-bundle plans are useful when the household’s needs are broadly similar; separate per-person plans are more flexible when one member (a senior parent, a chronic-condition adult, a new baby) needs a different tier. Compare both structures for a household of your shape rather than defaulting to one.
Portability, employer changes and moving city
NHIA cover tied to your employer usually ends when you leave the job, though the NHIA Act 2022 encourages continuity through informal-sector re-enrolment. State schemes are tied to the state; if you move from Lagos to Oyo, you may need to enrol with the new state scheme rather than carry your Lagos cover across. Private plans are contracts between you and the HMO, so they travel with you when you change jobs or move city, as long as the HMO’s network covers where you are going.
Complaints, service level and NHIA’s role
NHIA is the regulator for both routes, so complaints against an HMO — public scheme or private plan — go through the same channels. Practically, private-plan customers often report faster call handling and shorter authorisation times, because the HMO’s commercial reputation depends on it. Public-scheme service quality varies by HMO and by state, and the reader should treat provider service level as a genuine comparison factor rather than assume it is the same everywhere.
Which route for which household
None of the following is a promise about your specific situation; it is a decision framework. Confirm current terms with your HMO or on the NHIA website before enrolling.
- Federal or state public-sector employee. Start with the NHIA Formal Sector Scheme (FSSHIP) or the relevant state scheme — you are usually enrolled by default. Consider a private top-up plan if your household regularly uses services the public package caps (advanced imaging, specialist consults, private-hospital admissions).
- Private-sector employee whose employer offers group cover. Your group cover is almost always a private HMO plan. Use it, and use the informal NHIA route only if you specifically need it for a dependant not on your group plan.
- Self-employed, freelancer or informal-sector earner. Enrol in your state health insurance scheme for the core safety net. If your budget allows, add a private individual or family plan for wider hospital access, faster service and richer benefits.
- Family with young children. Combine the two: NHIA for immunisations and routine primary care, a private family plan for admissions, faster referrals and predictable hospital access.
- Family caring for an older parent. Enrol the parent in the relevant NHIA scheme where possible, and add a private senior-citizen plan from an HMO whose network is strong in your city. Do not rely on a single low-tier plan.
- High earner or household with international travel. A top-tier private plan with evacuation and specialist access will do more than a public scheme, but keep NHIA registration too so you retain the regulator-backed baseline.
- Household on a very tight budget. Enrol in the NHIA state or informal scheme, apply for Vulnerable Group Fund support if you qualify, and only add a private plan when your finances allow.
For most Nigerian households, the honest answer is not “either/or” — it is “start with NHIA, add private cover as your budget and needs allow”.
nairaCompare Insight
nairaCompare Insight
For the reader in a formal job, most of the “NHIS vs private HMO” comparison is decided for you: you have NHIA through work, and the useful question is whether to buy a private top-up. Pay for the top-up only if you have specifically identified services your current package will not cover — a private hospital you actually want to use, a chronic condition, family planning around a new baby.
For the reader who is self-employed, informal-sector or between jobs, treat the NHIA state scheme (or informal scheme) as your safety net and a private plan as your service upgrade. The NHIA scheme protects you from the worst outcomes; the private plan buys speed, network and comfort. Neither is a full substitute for the other.
Compare private HMO plans on nairaCompare
If your reading of the above points you towards adding a private plan, use the nairaCompare Health Insurance marketplace to compare current premiums, benefit ceilings and hospital lists side by side, then apply for the plan that fits.
Compare private Health Insurance plans
Current premiums, networks and benefit ceilings from NHIA-accredited HMOs, side by side.
Compare Health PlansFrequently Asked Questions
Is NHIS the same thing as NHIA?
Not quite. NHIA is the regulator created by the NHIA Act 2022; it replaced the old NHIS (National Health Insurance Scheme) as the governing body. What most people still call “NHIS” is the set of public schemes now run under NHIA — the Formal Sector Scheme, state schemes, informal-sector schemes and vulnerable-group cover. Every HMO in Nigeria, public or private, is now accredited by NHIA.
Can I use NHIA cover and a private plan at the same time?
Yes. You are not forced to choose one. Many households run NHIA cover through work or the state scheme for primary care and use a private HMO plan for wider hospital access, faster service and higher benefit ceilings. Keep both cards on you and use the plan that best matches the treatment you are seeking.
Are private HMO plans more expensive than NHIS?
Almost always, at the same level of cover. Public NHIA schemes are subsidised (by the employer, the state or the Vulnerable Group Fund), so the out-of-pocket contribution is low. Private plans are priced at market and compete on the size of the benefit package. Confirm current premiums on the nairaCompare listing before you decide.
If I already have NHIS at work, do I still need a private plan?
Not necessarily. Look at three things: the hospitals on your NHIA network, the services capped or excluded in your package, and the way your household actually uses healthcare. If your household is generally low-cost and you are happy with your assigned hospital, you may not need more. If you routinely need a private hospital, specialist reviews or a higher benefit ceiling, a private top-up plan is worth pricing.
Which is better for a family with young children?
For most Nigerian families with young children, the practical answer is NHIA cover plus a private family plan. NHIA handles immunisations, routine antenatal care and common childhood illnesses at low cost; a private family plan gives you wider hospital access and predictable admissions cover when the household needs more than routine care.
How do I check my NHIS or NHIA enrolment?
Enrolment is managed by your HMO and recorded on NHIA’s platform. Start with your HMO’s member portal or customer line, then confirm on the NHIA site if you need to. Our walkthrough of how to use the NHIA self-service portal covers registration checks, login and the e-ID in detail. If you cannot locate a record, ask your employer’s HR or the state scheme office (for state cover) to pull it for you.
Does the NHIA Act 2022 force me to buy a plan?
The Act makes health insurance mandatory in principle for every Nigerian and legal resident and gives NHIA a stronger enforcement mandate. In practice, enforcement is being rolled out gradually. It is safer, cheaper and simpler to enrol in the scheme that fits your situation now rather than wait to be enrolled by default.
Related Resources
• NHIS and the NHIA Act 2022 Explained: What Mandatory Health Insurance Means for You
• How to Use the NHIA (formerly NHIS) Self-Service Portal: Registration Checks, Login and E-ID (2026)
• State Health Insurance Schemes in Nigeria Explained: Lagos, Oyo, Anambra, FCT and More (2026)
Terms and conditions apply. Health-plan benefits, limits, exclusions, waiting periods, provider access and pre-existing-condition rules vary by plan and may change. Review current plan terms or confirm details with the relevant HMO, your employer or the National Health Insurance Authority (NHIA) before enrolling. This article provides general information and is not medical advice.
About Author
Noella Lepdung
Noëlla Lepdung is a writer who makes magic with all sorts of content, helping businesses find their voice and meet their ambitions with cutting-edge but human-first advertising. Her portfolio features brands such as Budweiser, The Coca-Cola Company, Nivea, Leadway Group, Honeywell Foods, Monieworx, Kimberly-Clark, and WAMCO.


Other related articles