









How to Use the NHIA (formerly NHIS) Self-Service Portal: Registration Checks, Login and E-ID (2026)
Author Noella Lepdung
Introduction
The National Health Insurance Authority now runs a self-service portal that lets Nigerians enrol, check their status, log in and manage their cover online without visiting an office. If you have been searching for the NHIS portal, that is the same system: the scheme was renamed from NHIS to NHIA in 2022 under the NHIA Act, but the public and many search results still use the old name.
This guide explains what the portal does, how to register, how to sign in, how to check whether you are already enrolled, and how to pick up your electronic ID card. It is written for informal-sector workers, small-business owners and salaried Nigerians who want to sort out their cover themselves.
Key takeaways
The NHIA portal is a genuine self-service alternative to office visits. You will need your NIN, a working phone and email, a passport photo, and (if you pay yourself) a Remita-ready card. New enrolees pick an HMO and primary hospital from the accredited list; existing enrolees should do a status check before starting a fresh record.
What the portal is, and who runs it
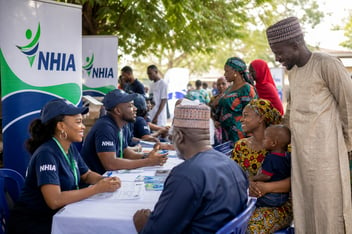
The portal is the NHIA’s self-service window into the national health insurance system. It was launched in September 2025 as part of the NHIA’s push to reduce the queues and paperwork that used to slow enrolment down. Through the portal, an enrolee can start a new enrolment, add a spouse or child, change their assigned healthcare provider, check the status of an application, and access their electronic membership record.
The Authority behind it is the National Health Insurance Authority, established under the NHIA Act 2022. If you want the fuller picture of what the NHIA replaced, why the old NHIS was reformed, and what the 2022 Act means for you in a country where cover is now framed as mandatory, see our 2026 NHIA (formerly NHIS) enrolment guide alongside this walk-through. Our pillar on the NHIA Act 2022 and what mandatory health insurance means for you sits above both and covers the legal picture; this article focuses only on how to actually use the portal.
Before you start: what to have ready
The portal will ask for identifying information and, in most cases, payment. Getting these in one place first will save you multiple restarts:
Your account is tied to these, and the portal sends you a one-time code to confirm you own them. Use the email you actually read, not an old one you have lost access to.
The National Identity Number is the anchor for most federal enrolments now. Some routes may also ask for BVN, so have both to hand if you can.
A clear passport-style photo, saved on the device you will use.
Formal-sector Nigerians are usually enrolled through their employer, which changes the flow. If you are covered under the Organised Private Sector arrangement, your HR or benefits contact will normally start the process; the portal is then used to view and manage your record rather than to initiate cover.
Informal-sector, self-employed and voluntary enrolees typically pay their contribution through Remita, the federal payment gateway. Have your card or bank app ready.
The scheme runs through NHIA-accredited HMOs and their listed hospitals. Knowing which HMO you want, and which primary hospital you would rather attend, makes the choice screen quicker.
You do not need all of this before you land on the site, because you can start, save and come back. It is simply easier not to.
Registering as a new enrolee
The portal opens with different entry points depending on your status: new enrolee, existing member, employer or healthcare provider. If you are enrolling for the first time, choose the new-enrolee route.
The registration flow follows a familiar shape. You create an account with your email and phone, verify both with the codes the portal sends, then enter your personal details as they appear on your NIN record. The portal will ask which route applies to you: formal (through an employer), informal-sector individual, vulnerable-group programme, or one of the specialised schemes such as the Group Individual and Family Social Health Insurance Programme for the non-formal population. Pick the one that matches your situation honestly, because it changes the contribution and the paperwork.
You will then be asked to choose or confirm an HMO from the NHIA-accredited list, and a primary healthcare facility from that HMO’s network. This choice matters. Your HMO handles pre-authorisations, referrals and complaints, and your primary facility is where most of your day-to-day care will be routed. Pick a hospital you can actually reach.
Where a contribution is due, the portal will hand you off to Remita to pay. Complete the payment there and return to the portal to confirm.
If a step hangs or a code does not arrive
Do not restart the whole flow. The portal keeps a draft, and the NHIA’s contact centre and social channels are the correct routes to get a stuck record moved forward.
Checking whether you are already enrolled
Many Nigerians have been enrolled at some point through an employer, an NYSC posting or a state scheme without realising the record still exists. Before you start a fresh registration, use the portal’s status-check option: sign in with your NIN or an existing membership number and see whether an active record already exists in your name.
If you find a record you did not know about, the portal lets you claim it, update your contact details, and reissue an electronic ID rather than duplicate the account. Duplicating enrolments causes reconciliation problems later, particularly when an employer or HMO tries to attach you to a group scheme.
Logging in
Returning enrolees sign in with the email or phone number they registered with, plus their password. If two-factor authentication is on, the portal will send a code to your registered phone or email. If you have forgotten your password, use the reset link on the sign-in page rather than opening a new account, which would duplicate you in the system.
The dashboard, once you are in, shows your active status, your assigned HMO, your primary hospital and your dependants. Most of the day-to-day actions live in that same dashboard: adding a spouse or child, changing your HMO or provider, updating your address, and checking that your contribution is up to date.
Getting your electronic ID (E-ID)
Once your enrolment is confirmed and any contribution has been paid, the portal issues an electronic membership ID. That is the record hospitals check to confirm you are on the scheme, and it is enough to access care while you wait for any physical card the HMO may issue.
Save the E-ID to your phone as a PDF or a screenshot, and note down your membership number separately. If you ever need to switch HMOs, that number travels with you: one of the aims of the NHIA Act 2022 was to make switching easier than it used to be under the old NHIS.
Common problems and honest fixes
The portal is still new and the traffic through it is heavy. A few patterns come up often:
- The verification code does not arrive. Check the phone number and email you entered against your NIN record, and check your spam folder. If nothing arrives after a second try, wait ten minutes rather than repeatedly re-triggering, which can lock the number.
- The system says you are already enrolled. Do a status check with your NIN. It is usually a legacy record that can be recovered, not a duplicate.
- The Remita payment succeeded but the portal has not updated. Keep the Remita reference number. Payment reconciliations sometimes take a working day. Do not pay again.
- The HMO or hospital you want is not on the list. The list only shows currently accredited NHIA providers. If yours is missing, they are either not accredited or their accreditation has lapsed. Choose from the current list; you can change later.
If what the screen says does not match what has actually happened to your record, the NHIA’s call centre and email, and the HMO’s own service line, are the appropriate routes. The portal is a self-service layer over the real scheme; it is not the whole scheme.
Where the portal fits into the wider decision
The NHIA scheme is the country’s default social health insurance, and under the NHIA Act 2022 cover is framed as mandatory for every Nigerian and legal resident. Enrolling through the portal is the low-cost, government route into that system. If your enrolment is actually happening at state level rather than federal, our guide to state health insurance schemes in Nigeria walks through how LASHMA, OYSHIA, ASHIA, FHIS and the other state agencies run their own portals and tiers. The portal is a sensible starting point for many households, particularly informal-sector workers and small-business owners who previously had nothing.
It is not the only route. Households often layer a private HMO plan on top of, or instead of, the national scheme, either because the hospital network they want is wider on the private side, or because the specific benefits they need (maternity, dental, chronic conditions) are structured differently in a private plan. Our comparison of NHIA (formerly NHIS) versus private HMO plans works through cost, coverage, network and waiting periods for the two routes side by side.
Compare accredited Health Insurance plans
See current premiums, networks and benefits from NHIA-accredited providers side by side.
Compare Health PlansFrequently Asked Questions
Is NHIS the same as NHIA?
Effectively, yes. The National Health Insurance Scheme was replaced by the National Health Insurance Authority in 2022 under the NHIA Act. The old NHIS branding still turns up on some pages, in URLs and in Nigerian search behaviour, but the current body is the NHIA. The self-service portal is the NHIA’s.
Do I have to pay something at enrolment?
It depends on your route. Formal-sector employees are covered through employer contributions. Informal-sector, voluntary and family enrolees pay a contribution, typically through Remita. Some vulnerable-group programmes are subsidised. The portal will show what applies to your chosen route before you commit.
Can I enrol my parents or dependants through the portal?
Yes. The portal supports adding dependants to a principal enrolee’s record. The number of dependants your contribution covers, and how additional dependants are treated, depends on the programme you enrol under.
What if I already have a private HMO plan?
You can still enrol on the NHIA. The two are not mutually exclusive. Many households keep a private plan for its network and use NHIA enrolment to meet the mandatory-cover framework.
Does the portal replace visiting an NHIA office?
For most transactions, yes. The Authority has been clear that the portal is a genuine alternative to office visits, not a supplement. Office visits remain available for edge cases and for people who prefer to be seen in person.
Related Resources
• NHIS and the NHIA Act 2022 Explained: What Mandatory Health Insurance Means for You
• 2026 NHIA (formerly NHIS) enrolment guide
• State Health Insurance Schemes in Nigeria Explained: Lagos, Oyo, Anambra, FCT and More (2026)
Terms and conditions apply. Health-plan benefits, limits, exclusions, waiting periods and portal features under the NHIA scheme may change from time to time. Confirm the current position on the NHIA website or with your HMO before enrolling. This article provides general information and is not medical or financial advice.
About Author
Noella Lepdung
Noëlla Lepdung is a writer who makes magic with all sorts of content, helping businesses find their voice and meet their ambitions with cutting-edge but human-first advertising. Her portfolio features brands such as Budweiser, The Coca-Cola Company, Nivea, Leadway Group, Honeywell Foods, Monieworx, Kimberly-Clark, and WAMCO.


Other related articles